Ask any Magistrate who runs a Section 138 board what kills these complaints and the answer is rarely the drafting. It is the dates. A notice counted from the wrong day. A complaint filed on day twelve of the drawer's fifteen. Neither mistake can be cured by an amendment application, and the client, who has already waited a year, finds out at the stage of cognizance.
So this piece starts with the calendar. Every period in a cheque dishonour matter is set out below with the provision or the judgment that fixes it, then worked through on real dates. The three places practitioners most often go wrong get their own section. The demand notice itself comes at the end, complete, with nothing to sign up for.
The four periods, end to end
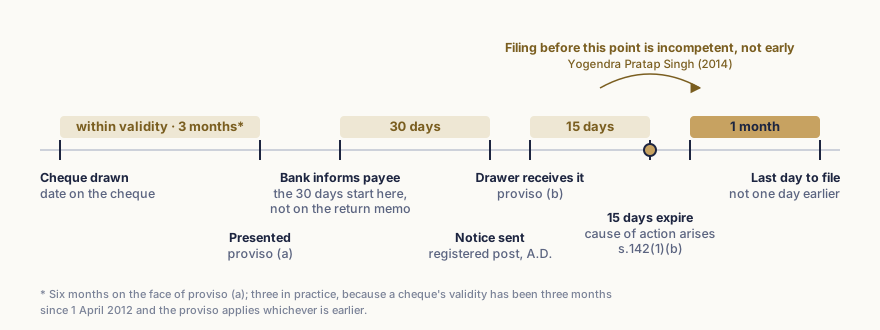
| # | Step | Period | Runs from | Authority |
|---|---|---|---|---|
| 1 | Present the cheque | 6 months on the statute; 3 months in practice | date the cheque is drawn | s.138 proviso (a); RBI circular of 4 Nov 2011, effective 1 Apr 2012 |
| 2 | Cheque returned unpaid | — | — | s.138 |
| 3 | Issue written demand notice | 30 days | receipt of information from the bank that the cheque was returned | s.138 proviso (b) |
| 4 | Drawer's window to pay | 15 days | receipt of the notice by the drawer | s.138 proviso (c) |
| 5 | Cause of action arises | on expiry of step 4 | — | s.138 proviso (c) with s.142(1)(b) |
| 6 | File the complaint | 1 month — and not before step 4 expires | date the cause of action arose | s.142(1)(b) |
| 7 | Delay condonable? | Yes, on sufficient cause | — | proviso to s.142(1)(b), in force 6 Feb 2003 |
Worked through on dates
Take a cheque dated 1 June 2026. The dates below follow the counting rule the Supreme Court applied in Saketh India Ltd v. India Securities Ltd, AIR 1999 SC 1090: the day on which a period starts is excluded and the last day is included. In Saketh the notice was served on 29 September, the fifteen days ran out on 14 October, and a complaint filed on 15 November was held to be in time. The example uses the same arithmetic.
| Event | Date | How it is counted |
|---|---|---|
| Cheque drawn | 1 June | Validity runs to 31 August (three months) |
| Presented; returned unpaid | 12 June | Within validity |
| Bank's intimation received by payee | 15 June | The 30 days start here |
| Last day to send the notice | 15 July | 15 June excluded; day 30 is 15 July |
| Notice sent by registered post A.D. | 22 June | Well inside the window; keep the receipt |
| Notice received by drawer | 29 June | The 15 days start here |
| Drawer's 15 days expire | 14 July | 29 June excluded; day 15 is 14 July |
| Cause of action arises | 15 July | The day after the fifteen days run out |
| Earliest day to file | 15 July | Not 14 July, not 10 July |
| Last day to file | 15 August | One month from the cause of action, 15 July excluded |
Two things to notice. The notice went out on 22 June, twenty-three days before the statutory last day, and there was no reason to use those days. And the complaint window opened on 15 July and closed on 15 August: a month, not thirty days, which matters in a thirty-one-day month.
Where the arithmetic goes wrong
The thirty days run from the bank's information, not the cheque's return. Proviso (b) gives thirty days from "the receipt of information by him from the bank regarding the return of the cheque as unpaid." Not the date on the return memo, not the date the cheque was drawn. If your client learned of the dishonour a week after the memo was issued, that week is yours, and paragraph 5 of the notice should say on what date the intimation was received so that the defence cannot argue the point later.
Thirty days is also the current figure. It was fifteen until the Negotiable Instruments (Amendment and Miscellaneous Provisions) Act 2002 substituted thirty, with effect from 6 February 2003. Older precedent books say fifteen, and so do a surprising number of templates still doing the rounds.
The complaint window has a floor as well as a ceiling. Section 142(1)(b) requires the complaint within one month of the cause of action, and the cause of action arises only when the drawer's fifteen days expire. A complaint filed on day ten is not early. It is incompetent.
The authority is Yogendra Pratap Singh v. Savitri Pandey, (2014) 10 SCC 713, decided by three judges. The Court held that no complaint can be filed before the fifteen-day period has elapsed and that the court is "barred in law from taking cognizance of such complaint." The defect is not cured by the fact that fifteen days have passed by the date the Magistrate applies his mind. The Court left one door open: the payee may file a fresh complaint within one month of the decision in the criminal case, and the delay will be treated as condoned under the proviso to Section 142(1)(b).
Six months is not six months. Proviso (a) says the cheque must be presented "within a period of six months from the date on which it is drawn or within the period of its validity, whichever is earlier." That text has never been amended. But since 1 April 2012, under the RBI's circular of 4 November 2011 issued under Section 35A of the Banking Regulation Act 1949, banks do not pay cheques presented more than three months after their date. The cheque's period of validity is therefore three months; three is earlier than six; three months is the operative window.
The point matters in the drafting. A notice that says "Section 138 requires presentation within three months" misstates the section, and an alert defence counsel will say so. The correct formulation is that the cheque was presented within its period of validity, which is the earlier of the two limbs.
What has to be true before you send anything
K. Bhaskaran v. Sankaran Vaidhyan Balan, (1999) 7 SCC 510, decided on 29 September 1999 by Thomas and Shah JJ., still supplies the standard analysis. The offence has five components: drawing of the cheque; presentation of the cheque to the bank; return of the cheque unpaid by the drawee bank; notice in writing to the drawer demanding payment; and failure of the drawer to pay within fifteen days of receipt of the notice.
The same judgment supplies the distinction that decides most service disputes:
"'Giving notice' in the context is not the same as receipt of notice. Giving is a process of which receipt is the accomplishment."
Two further conditions are easy to overlook. The cheque must have been issued for the discharge, in whole or in part, of a debt or other liability, and the Explanation to Section 138 confines that to a legally enforceable debt. A cheque given as a gift, as security for an unenforceable claim, or against a time-barred debt will not sustain the offence. And the complaint must be in writing, by the payee or the holder in due course: Section 142(1)(a).
Service, refusal and the unclaimed envelope
Send the notice by registered post with acknowledgement due, to the correct address, and keep the receipt. That is what triggers the presumption.
Section 27 of the General Clauses Act 1897 raises a considerably stronger presumption than Section 114 of the Evidence Act. In C.C. Alavi Haji v. Palapetty Muhammed, (2007) 6 SCC 555, a three-judge bench held that where the notice is sent by registered post to the correct address, "unless and until the contrary is proved by the addressee, service of notice is deemed to have been effected at the time at which the letter would have been delivered in the ordinary course of business", and that the complainant need not plead that the accused evaded service or had a hand in the notice coming back unserved.
The Court then closed the obvious escape route:
"A person who does not pay within 15 days of receipt of the summons from the Court along with the copy of the complaint under Section 138 of the Act, cannot obviously contend that there was no proper service of notice."
Where the envelope comes back unclaimed, K. Bhaskaran treats the date of return as the commencing date for reckoning the fifteen days under proviso (c), without prejudice to the drawer proving he genuinely had no knowledge of it.
If the notice lapses, you can present again
A missed deadline on one dishonour is not the end of the matter. In MSR Leathers v. S. Palaniappan, (2013) 1 SCC 177, three judges overruled Sadanandan Bhadran v. Madhavan Sunil Kumar, (1998) 6 SCC 514, and held:
"prosecution based upon second or successive dishonour of the cheque is also permissible so long as the same satisfies the requirements stipulated in the proviso to Section 138"
A fresh presentation, a fresh dishonour, a fresh notice and a fresh failure to pay generate a fresh cause of action, even where nothing was filed on the first default. The constraint is the cheque's own validity, which is why the three-month rule in step 1 governs how many attempts you realistically have. A cheque dated 1 June presented on 12 June and again on 20 August has used up most of its life; there will not be a third go.
Where to file, and what the Magistrate now does first
Section 142(2), inserted by the Negotiable Instruments (Amendment) Act 2015 with retrospective effect from 15 June 2015, fixes territorial jurisdiction. If the cheque was delivered for collection through an account, the complaint lies where the branch at which the payee maintains that account is situated. If it was presented for payment otherwise than through an account, it lies where the branch of the drawee bank at which the drawer maintains his account is situated.
This reversed Dashrath Rupsingh Rathod v. State of Maharashtra, (2014) 9 SCC 129, which had confined jurisdiction to the drawee bank's location. In Bridgestone India Pvt Ltd v. Inderpal Singh, (2016) 2 SCC 75, the Supreme Court confirmed that Dashrath Rupsingh "would not stand in the way", the deeming language in Section 142A carrying the new regime into pending matters.
Since 1 July 2024 the complaint is processed under the Bharatiya Nagarik Suraksha Sanhita rather than the CrPC, and one change is easy to miss. Examination of the complainant, which was Section 200 CrPC, is now Section 223 BNSS, and the first proviso to Section 223(1) provides that "no cognizance of an offence shall be taken by the Magistrate without giving the accused an opportunity of being heard." Expect a pre-cognizance hearing that did not exist under the old code, and expect the registry to want the original cheque, the return memo, the postal receipt and the returned envelope or A.D. card with the complaint. (The other CrPC to BNSS pairs a cheque practice runs into are in our section map.)
Interim compensation: two rules that look alike and are not
The Negotiable Instruments (Amendment) Act 2018, in force from 1 September 2018, added two provisions that are routinely conflated.
| Section 143A | Section 148 | |
|---|---|---|
| Stage | Trial, before conviction | Appeal, after conviction |
| Amount | Shall not exceed 20% — a ceiling | Minimum of 20% — a floor |
| Payable within | 60 days, +30 on sufficient cause | 60 days, +30 on sufficient cause |
| Applies to pre-2018 complaints? | No — prospective only | Yes |
| Is "may" discretionary? | Yes, genuinely | Generally read as a rule |
The asymmetry is deliberate and the Supreme Court has explained it. Section 143A operates before any finding of guilt, so in Rakesh Ranjan Shrivastava v. State of Jharkhand, 2024 INSC 205 the Court held that "may" there is directory and cannot be read as "shall". Section 148 operates after conviction, and in Surinder Singh Deswal v. Virender Gandhi, (2019) 11 SCC 341, the same word was construed as a rule, with a refusal to order deposit being the exception for which reasons must be given.
On retrospectivity the split runs the other way from what most practitioners assume. Section 143A is prospective only, because it creates a new liability before guilt is established (G.J. Raja v. Tejraj Surana, 2019). Section 148 applies to appeals even where the complaint was filed before 1 September 2018 (Deswal again).
The notice
What follows is a complete demand notice under proviso (b) to Section 138, drafted for the common case: a cheque issued against an admitted debt, returned for insufficient funds. Replace the bracketed fields and delete what does not apply.
                    [ADVOCATE'S LETTERHEAD]

                                          Ref. No.: ____________
                                          Date: ______________

BY REGISTERED POST WITH ACKNOWLEDGEMENT DUE
AND BY SPEED POST

To,
[Full name of the drawer]
S/o, D/o, W/o [____________]
[Complete postal address as it appears in your client's records
and on the cheque]

              LEGAL NOTICE UNDER SECTION 138 OF THE
              NEGOTIABLE INSTRUMENTS ACT, 1881

Sir/Madam,

Under instructions from and on behalf of my client, [Full name of
payee], [S/o, D/o, W/o ______ / a company incorporated under the
Companies Act, 2013 and having its registered office at ______],
residing at / having its office at [complete address] (hereinafter
"my client"), I address you as follows:

1.  That my client and you have been [describe the relationship:
    e.g. "engaged in business dealings since ______" / "known to
    each other since ______"].

2.  That [set out the transaction giving rise to the debt with
    precision: e.g. "on ______ my client supplied to you goods
    under Invoice No. ______ dated ______ for a sum of
    Rs. __________/- (Rupees ____________________ only), which
    sum became due and payable on ______"]. The said sum
    constitutes a legally enforceable debt owed by you to my
    client.

3.  That in discharge of the said liability, you issued to my
    client Cheque No. __________ dated ______ for a sum of
    Rs. __________/- (Rupees ____________________ only), drawn on
    [name of drawee bank], [branch and address], from Account
    No. __________ maintained by you with the said bank
    (hereinafter "the said cheque").

4.  That my client presented the said cheque for encashment
    through his/its bank, [name of payee's bank], [branch and
    address], where my client maintains Account No. __________,
    on ______, being within the period of its validity.

5.  That the said cheque was returned unpaid by the drawee bank
    vide Cheque Return Memo dated ______ bearing the reason
    "[reproduce the reason exactly as printed on the memo, e.g.
    'FUNDS INSUFFICIENT']". My client received intimation of the
    said dishonour from his/its bank on ______.

6.  That the dishonour of the said cheque establishes that you
    had no sufficient funds in the said account to honour the
    cheque, and that you have failed and neglected to discharge
    your legally enforceable liability to my client.

7.  That the said cheque having been issued in discharge of a
    legally enforceable debt and having been returned unpaid for
    insufficiency of funds, you have committed an offence
    punishable under Section 138 of the Negotiable Instruments
    Act, 1881.

    NOW THEREFORE, by this notice, and in terms of clause (b) of
the proviso to Section 138 of the Negotiable Instruments Act,
1881, I call upon you to pay to my client the sum of
Rs. __________/- (Rupees ____________________ only), being the
amount of the said cheque, WITHIN FIFTEEN (15) DAYS of the receipt
of this notice, by way of demand draft or electronic transfer in
favour of my client.

    TAKE NOTICE that in the event of your failure to make payment
of the aforesaid sum within the said period of fifteen days, my
client shall be constrained to initiate criminal proceedings
against you under Section 138 of the Negotiable Instruments Act,
1881, before the competent court, wherein you shall be liable to
be punished with imprisonment for a term which may extend to two
years, or with fine which may extend to twice the amount of the
cheque, or with both, entirely at your own risk as to costs and
consequences.

    TAKE FURTHER NOTICE that my client also reserves the right to
initiate such civil proceedings for recovery of the said sum
together with interest and costs as may be available in law.

    A copy of this notice is retained in my office for record and
further necessary action.

                                        [Signature]
                                        [Name], Advocate
                                        Enrolment No.: __________
                                        [Address]
                                        [Telephone] [Email]
Adapting it
The paragraph most worth your attention is paragraph 2. Everything else in the notice is mechanical; the description of the underlying liability is where the matter is won or lost, because the drawer's defence will almost always be that the cheque was not issued for a legally enforceable debt. Plead the transaction with the same particularity you would in a plaint.
If the return memo reads something other than insufficiency of funds ("account closed", "payment stopped by drawer", "signature differs"), reproduce it verbatim in paragraph 5 and do not paraphrase it into "insufficient funds". The reason on the memo is evidence, and altering it invites a needless argument.
If your client is a company, the notice should be issued on the authority of a board resolution or a power of attorney, and the complaint will need the authorised signatory pleaded properly.
One more thing, and it applies to the authorities cited in this piece as much as to any others. Read the judgment before you put it in a complaint or a written submission. Each one above is linked to its text for that reason, and since July 2026 the Supreme Court has said in terms that citing a judgment without verifying it is misconduct; what the courts have done about fabricated citations is a separate piece.
What Synapse does with this
Every deadline in this piece is arithmetic on dates that already exist somewhere in the file: the date on the cheque, the date on the return memo, the date your client told you. When these matters fail, it is nearly always the diary that failed, not the lawyer's understanding of the section.
Synapse takes those dates out of the consultation and puts them on the case timeline as it happens, so the thirty-day window and the fifteen-day window are computed from the record rather than reconstructed from memory a month later. When the notice is drafted from the case facts, each statutory reference in it opens to the provision, and each judgment cited is checked against IndianKanoon by name and by citation before it reaches you; one that cannot be matched is flagged rather than passed off as authority.
The notice above covers the ordinary case. A tool earns its place on the matter that is not ordinary, and on the fourth cheque matter of the week when the dates start to blur.
Statutory text quoted from the Negotiable Instruments Act 1881 as amended by Act 55 of 2002, Act 26 of 2015 and Act 20 of 2018 (the last brought into force on 1 September 2018 by S.O. 3995(E)), and from the Bharatiya Nagarik Suraksha Sanhita 2023 as published in the Gazette of India on 25 December 2023. The provisions and authorities were checked against the sources linked in the text on 28 September 2026. This article is general information, not legal advice, and does not create an advocate–client relationship. Verify every provision against the current bare act and read each judgment before relying on it.